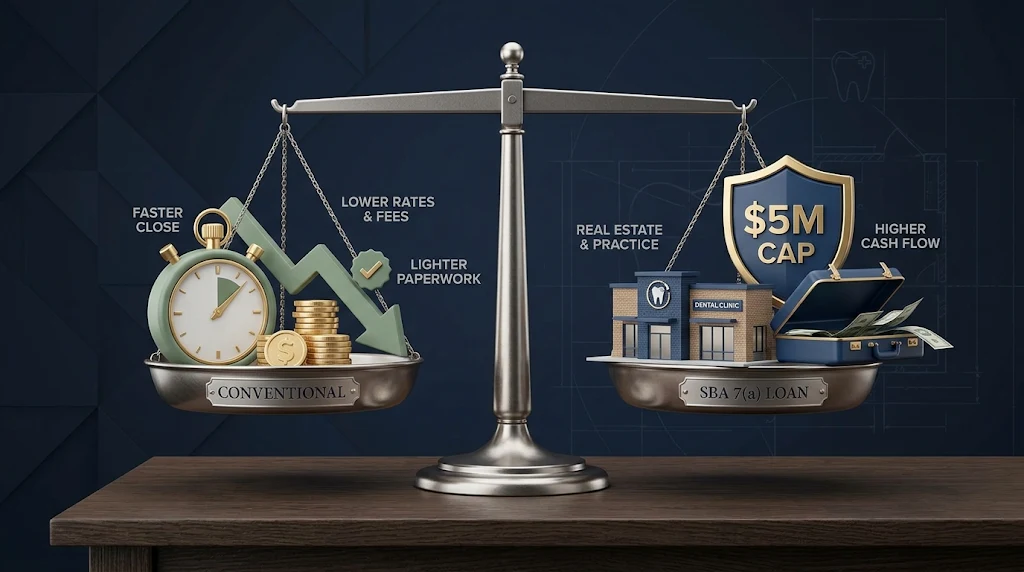
For most dental practice acquisitions, conventional financing should be the first stop, with an SBA 7(a) loan as a powerful backup when conventional terms or limits fall short. SBA financing is rarely the cheapest option, but it can be the best fit for large, complex deals or those with significant commercial real estate.
The right choice depends on three things: the buyer’s financial strength, the practice’s profitability, and the size and structure of the deal. This article compares the two options, explains how new SBA rules effective October 1, 2026, change the math on practice-plus-real-estate deals, and outlines what to expect in paperwork, fees, and guarantees.
SBA 7(a) vs. conventional: the key differences
The SBA 7(a) program exists for borrowers and deals that fall outside conventional lending guidelines. Because the federal government guarantees part of the loan, the lender takes on less risk and can finance larger or more complex transactions.
| Factor | SBA 7(a) loan | Conventional practice loan |
|---|---|---|
| Maximum loan size | Up to $5 million | Varies by lender; some dental programs cap below SBA limits |
| Interest rates | Often higher | Often lower |
| Fees | Additional SBA fees, including a guarantee fee | Fewer program-specific fees |
| Down payment | Equity injection generally required for a full business acquisition | Varies by lender and borrower strength |
| Practice amortization | Up to 10 years; longer when blended with real estate | Typically 10 years on the practice portion |
| Documentation | More extensive, to verify SBA eligibility | Lighter |
| Approval speed | Generally longer timelines | Generally faster |
| Personal guarantee | Unlimited guarantee from owners of 20% or more | Usually required as well |
In short, SBA financing trades higher cost and more friction for flexibility and capacity.
The October 1, 2026 change: no more 51% real estate exception
As of October 1, 2026, buyers can no longer finance an entire practice-plus-building acquisition over 25 years under the SBA’s 51% real estate exception. That exception no longer applies to business acquisitions.
Under the old rule, if commercial real estate made up at least 51% of the total deal, you could roll the practice and property into one SBA 7(a) loan amortized over 25 years. Spreading the full purchase price over that long a term kept monthly payments low.
Lenders now have two ways to structure these deals:
- Two separate loans: the practice over up to 10 years and the real estate over up to 25 years.
- One combined loan: a single loan using a weighted-average amortization based on the share of practice versus real estate.
Worked example
Consider a buyer acquiring a dental practice for $800,000 and its building for $1.2 million, a $2 million deal in which real estate is 60% of the total.
| Component | Price | Share | Maximum term |
|---|---|---|---|
| Practice | $800,000 | 40% | 10 years |
| Real estate | $1,200,000 | 60% | 25 years |
| Total | $2,000,000 | 100% |
The blended term weights each maximum by its share of the deal: (0.40 × 10) + (0.60 × 25) = 4 + 15 = 19 years.
Under the old rules, all $2 million could have been amortized over 25 years. Under the new rules, a combined loan comes in at roughly 19 years.
When SBA beats conventional, and when it doesn’t
A blended SBA 7(a) loan still has a clear edge when the deal includes a substantial building. Because the blended term is weighted toward the real estate, a larger property pushes the repayment period well past the standard 10-year practice loan.
In the example above, a 19-year blended term versus a conventional loan that repays the practice portion over 10 years can meaningfully lower monthly debt service. That frees up cash flow in the critical first years of ownership.
SBA tends to win when:
- The deal includes significant commercial real estate.
- The total financing need exceeds a conventional program’s lending limit, up to the SBA’s $5 million cap.
- The transaction is complex or falls outside conventional underwriting guidelines.
- Monthly cash flow matters more to the buyer than total borrowing cost.
Conventional tends to win when:
- The buyer is financially strong, and the practice is solidly profitable.
- The deal fits within conventional loan limits.
- The buyer wants a lower rate, fewer fees, and a faster close.
- There is little or no real estate to stretch the amortization.
Paperwork, fees, and personal guarantees
Expect more documentation, extra fees, and a longer path to closing with an SBA loan. Because the government guarantees part of the financing, the lender must confirm that both the buyer and the deal meet SBA eligibility rules.
Documentation. SBA files require more extensive paperwork than conventional practice loans. That added verification is the main reason SBA approvals and closings take longer than direct-practice lender approvals and closings.
SBA guarantee fee. The guarantee fee is based on the guaranteed portion of the loan, not necessarily the full loan amount. The fee schedule changes each fiscal year, so ask your lender for a written calculation using the FY 2027 schedule, effective October 1, 2026.
Personal guarantees. Anyone owning 20% or more of the borrowing business generally must sign an unlimited personal guarantee. This is not unique to SBA lending: most conventional dental acquisition lenders also require the buying dentist to personally guarantee the loan.
Real-world example: when the pricier loan was the right loan
In one acquisition, a buyer purchased an established dental practice together with a large commercial building. Several conventional lenders were willing to finance the deal, but they required shorter amortization on the practice portion, which meant much higher monthly payments.
SBA financing let the buyer combine the practice and real estate into one loan with a longer blended amortization. The SBA loan carried a higher interest rate and higher total borrowing costs, but the longer repayment period substantially reduced monthly debt service.
That cash flow mattered. The buyer planned to invest in new equipment, facility improvements, and practice growth right after closing. The SBA loan wasn’t the cheapest option, but it gave the buyer the liquidity to reinvest while comfortably carrying the debt.
The bottom line
Start with conventional financing, and keep SBA 7(a) in reserve for deals where conventional terms or limits don’t fit. For acquisitions with substantial real estate, a blended SBA loan can still offer a much longer repayment period than a standard practice loan, even after the October 2026 rule change.
Before committing, compare both options on monthly payment and total cost, request a written FY 2027 guarantee fee calculation, and weigh the trade-off against your post-closing plans for the practice.